Why Retirees Outlive Their Savings: The Longevity Risk Nobody Talks About
Living longer is a gift, but it strains retirement portfolios. Learn what longevity risk means and why it matters for financial planning.
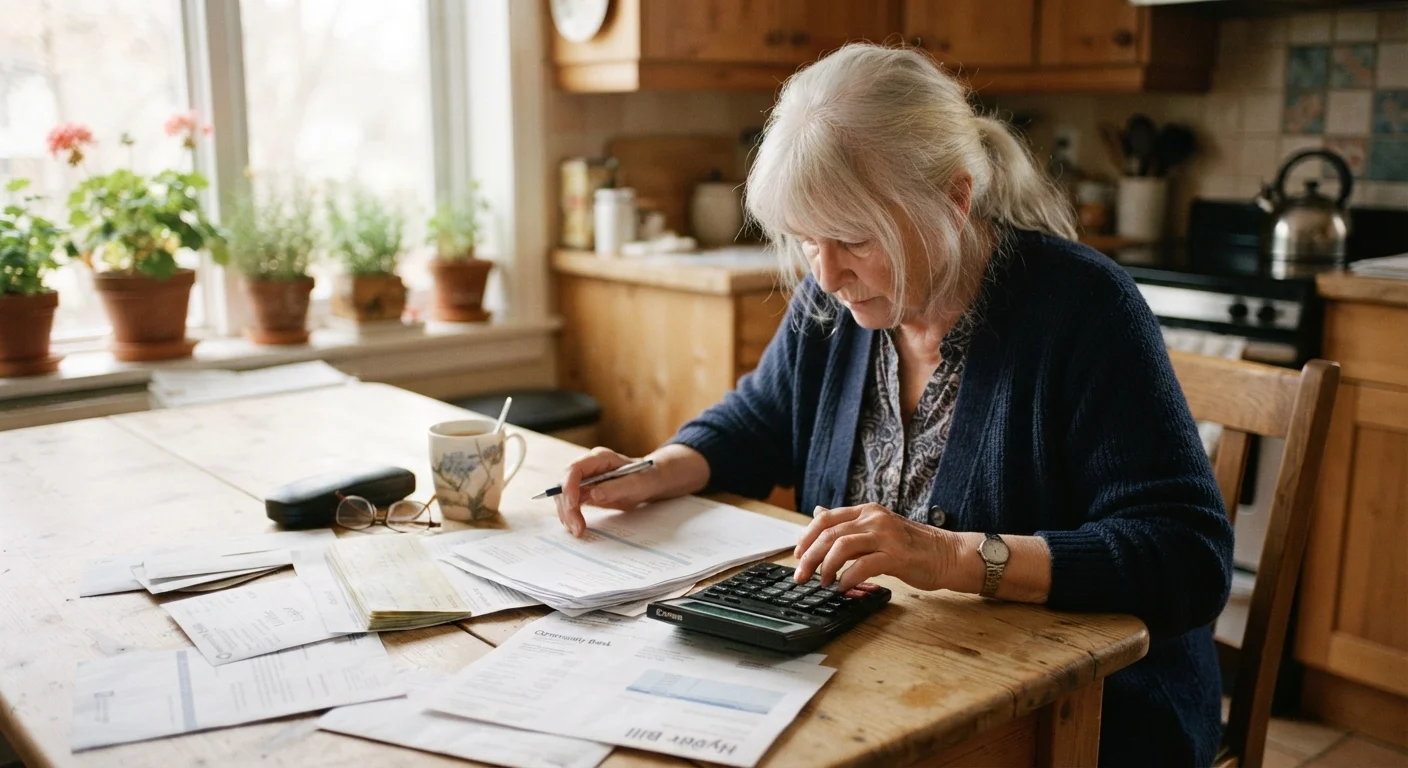
Photo: seetrueworth.net editorial
—— In This Article
Key Takeaways
- A 65-year-old American today has a meaningful probability of living into their late 80s or beyond.
- Most people significantly underestimate how long their retirement will last when they first retire.
- Healthcare costs tend to rise with age, putting extra pressure on savings in later retirement years.
- Delaying Social Security benefits can increase monthly income and reduce the risk of outliving other assets.
- Inflation quietly erodes purchasing power across a long retirement, compounding the savings shortfall.
- A licensed financial adviser can help model different longevity scenarios for your specific situation.
The gap between expected and actual retirement length
Most people retire with a number in mind: a savings balance, a monthly budget, a rough estimate of how many years they need to cover. The problem is that the estimate is often too short.
According to data published by the Social Security Administration, a 65-year-old man today can expect to live, on average, into his mid-80s. A 65-year-old woman can expect to live past her mid-80s. Roughly one in four 65-year-olds will live past 90. These are averages across large populations, so individual outcomes vary widely, but the pattern is consistent: retirement is longer than most people plan for.
That gap between expected and actual retirement length is the foundation of longevity risk. A portfolio built to last 15 years faces a very different challenge than one that must last 25 or 30. The math does not bend.
Common money myths that trip up retirees include the assumption that your savings just need to get you to your late 70s. For many people, that ceiling is decades too low.
Why healthcare costs amplify the problem
Healthcare spending tends to increase with age. In the earlier years of retirement, many people are relatively healthy and active. In their late 70s and 80s, chronic conditions, prescription costs, and the possibility of long-term care begin to weigh more heavily on spending.
Medicare covers many, but not all, medical expenses. Premiums, copays, dental care, vision, hearing, and most long-term care costs fall outside standard Medicare coverage. A retiree who budgets only for today's healthcare needs may face significant shortfalls a decade or two later.
Widespread beliefs about Medicare deserve scrutiny, particularly the assumption that it functions as comprehensive health insurance. It does not.
Model multiple time horizons
When reviewing a retirement plan, ask your financial adviser to model outcomes at age 85, 90, and 95. Seeing how your portfolio holds up across different lifespans often reveals gaps that a single average estimate misses. This is general guidance; your adviser can tailor the analysis to your specific situation.
The interaction between healthcare costs and a long retirement is one reason financial planners sometimes describe longevity risk as a multiplier: it does not just extend the drawdown period, it extends it into the years when costs are highest.
Inflation across a long retirement
A retiree at 65 who budgets carefully for their current expenses may still face a shortfall at 85 if inflation erodes purchasing power over those 20 years. Even at a modest annual inflation rate, the real value of a fixed income stream shrinks considerably across a multi-decade retirement.
Retirees who rely heavily on fixed income sources without any cost-of-living adjustment are most exposed. Social Security does include a cost-of-living adjustment, which is one reason understanding how inflation affects retirement income matters when thinking about which income sources to draw first.
Sequencing income sources strategically during retirement can affect how well a portfolio holds up against both inflation and longevity. The order in which you draw from savings, pensions, and Social Security has real long-term consequences.
Practical framing for managing longevity risk
Longevity risk cannot be eliminated, but it can be planned for. Several general concepts appear consistently in retirement planning literature, though how they apply depends on individual circumstances.
- Delaying Social Security benefits past your full retirement age increases the monthly payment and extends a guaranteed lifetime income stream.
- Maintaining some portfolio exposure to growth-oriented assets, even in retirement, can help offset the effects of inflation over a long time horizon, though this also involves market risk.
- Planning explicitly for healthcare costs, including potential long-term care needs, reduces the chance of late-retirement surprises.
- Reviewing withdrawal rates periodically, rather than setting them once and never revisiting, allows adjustments if circumstances change.
Rethinking your monthly budget after 60 is a practical starting point for aligning spending with the reality of a longer retirement.
For anyone within a decade of retirement, a structured pre-retirement financial checklist can help identify gaps before they become harder to close.
This article is for general informational and educational purposes only. It is not personalised financial, investment, tax, or legal advice. Retirement planning involves individual variables that this article cannot address. Consult a licensed financial adviser, certified financial planner, or other qualified professional before making decisions about your own retirement savings or income strategy.
Frequently Asked Questions
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile