Stretching a Fixed Income on the Road: Budget Strategies That Actually Hold Up
Practical approaches to keeping travel costs manageable on a fixed income, from timing your trips to understanding what discounts are widely available.
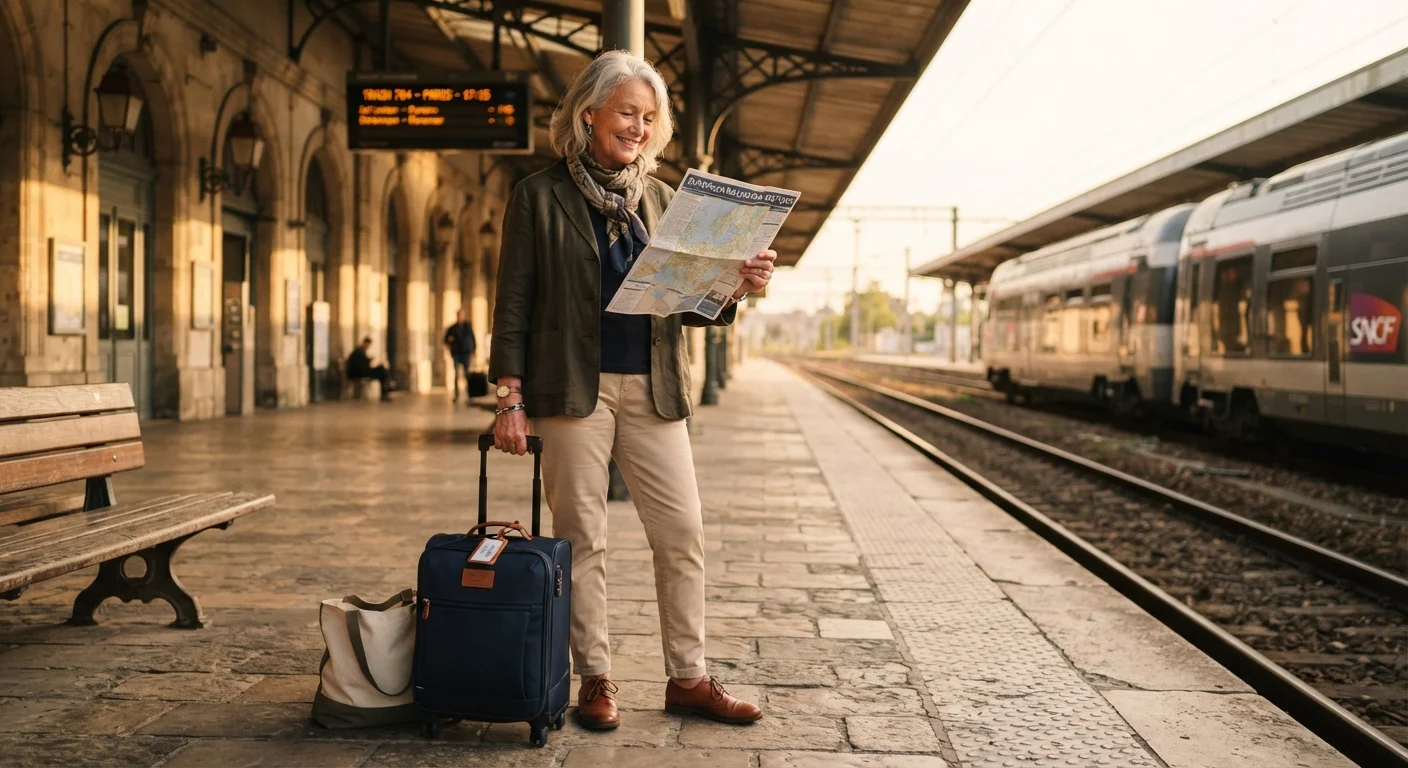
Photo: seetrueworth.net editorial
—— In This Article
Key Takeaways
- Traveling in the shoulder season can cut costs significantly without sacrificing experience.
- Senior discounts on rail, lodging, and parks exist widely but require verification at booking.
- A dedicated travel fund, built incrementally, makes trip costs predictable and manageable.
- Packing light reduces baggage fees and speeds up transit, lowering overall trip costs.
- Longer stays in fewer places often cost less than multi-city itineraries with frequent transit.
Why fixed-income travel planning is different
When income is fixed, the margin for financial surprises is narrow. A missed flight connection that costs $200 to fix, or a last-minute hotel upgrade because a booking fell through, can strain the whole trip budget. That is not a reason to stay home. It is a reason to plan with more precision than travelers who have larger financial buffers behind them.
The good news is that precision planning often produces a better trip regardless of income. Travelers who define a budget upfront, book ahead, and choose itineraries that fit their pace tend to return satisfied. Those who leave costs vague often overspend or cut experiences short. For anyone rethinking their monthly spending in retirement, travel can be a line item that holds up reliably when it is planned that way.
Practices that keep travel costs stable
The strategies below are not about deprivation. They are about knowing where money goes before it leaves your account.
Travel in the shoulder season rather than peak periods
Airfare, lodging, and tours all follow demand pricing. The weeks just before or after a destination's busiest period typically see lower prices with only minor differences in weather or crowds. For travelers on a fixed income, this timing difference can determine whether a trip is affordable at all.
Build a dedicated travel fund with automatic monthly transfers
Paying for a trip out of general savings creates budget pressure and can crowd out other expenses. A separate, labeled account that receives a fixed monthly deposit makes the cost of travel predictable and separates it from day-to-day spending. Setting aside money on a fixed income follows the same logic: small, consistent contributions add up.
Verify senior discount eligibility before assuming it applies
Senior discounts on rail passes, national park entry, and lodging are real and sometimes substantial, but eligibility ages, blackout periods, and booking windows vary widely. Assuming a discount applies without checking can lead to budget shortfalls at checkout. Understanding how senior travel discounts actually work prevents those surprises.
Choose longer stays in fewer locations over multi-stop itineraries
Every transit leg costs money: flights, trains, taxis, baggage handling, and the incidental expenses that come with arriving somewhere new. Spending five nights in one city instead of two nights each in three cities eliminates multiple transit costs and reduces the pace, which matters for physical stamina as well as budget.
Set a per-day spending ceiling and track it in real time
A total trip budget is harder to manage than a daily one. Breaking total spend into a per-day ceiling makes it obvious when a single day is running over budget, which allows for adjustment before the problem compounds. Many free budgeting apps support this without requiring financial account access.
Account for hidden costs before finalizing a destination
The sticker price of a flight or hotel rarely reflects the full trip cost. Visa fees, travel insurance, airport transfer costs, tipping norms, and currency conversion fees all add up. Planning gaps that derail senior travel often involve exactly these overlooked line items.
For a broader look at how these habits connect to everyday money management, the finance hub covers budgeting fundamentals that apply well beyond travel.
Quick actions you can take now
Planning a trip does not have to start with a destination. It can start with the financial foundation that makes any destination realistic.
Once finances are in order, it is worth revisiting your packing approach. Traveling with less luggage cuts baggage fees and speeds up every transit leg, which compounds into real savings over a multi-day trip.
This article provides general financial and travel information for educational purposes only and does not constitute personalized financial or travel advice. Consult a qualified financial adviser for guidance specific to your circumstances, and verify all travel details, including discount eligibility and entry requirements, directly with official sources before booking.
Travel Editorial Team
Travel Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile