Traditional IRA vs. Roth IRA: Which Structure Fits Your Retirement Timeline
A side-by-side look at how Traditional and Roth IRAs differ in tax treatment, withdrawal rules, and long-term planning considerations.
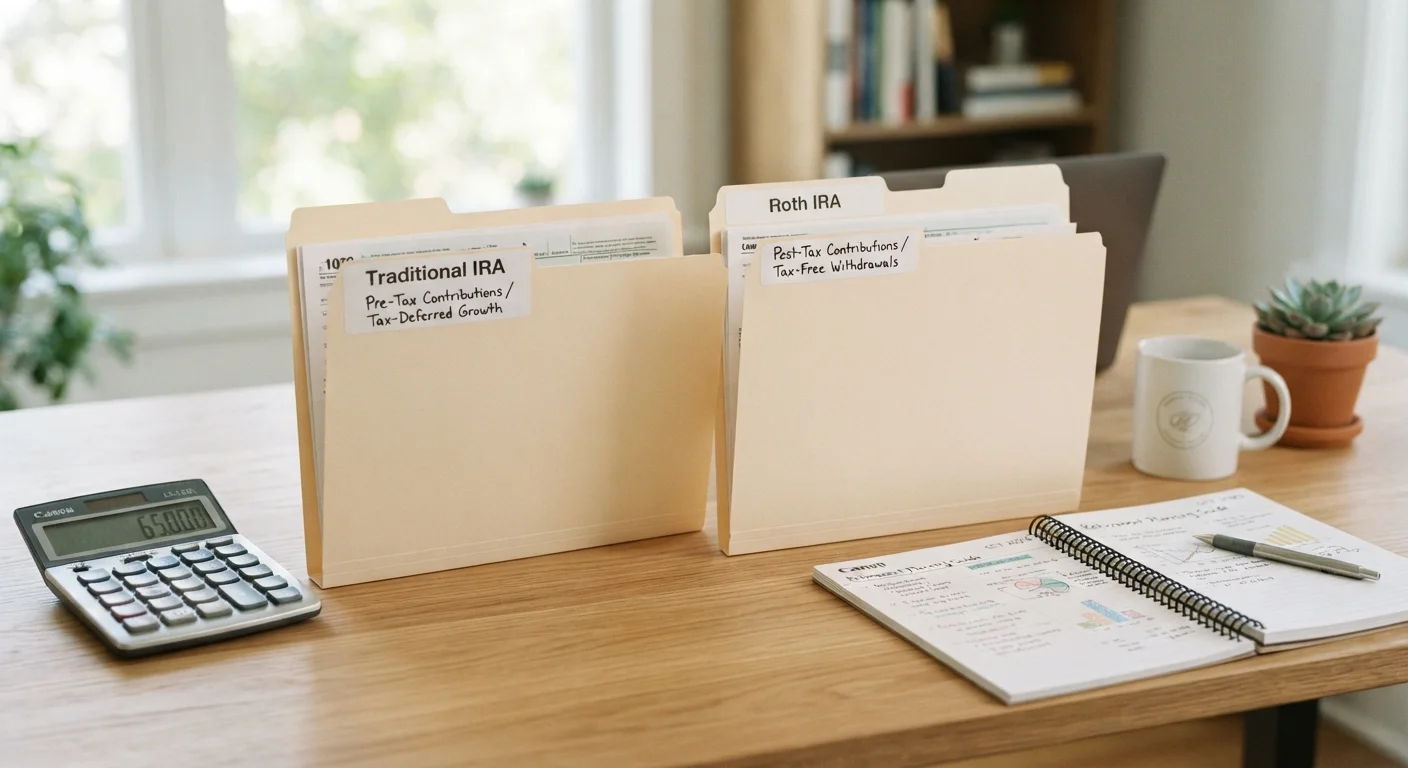
Photo: seetrueworth.net editorial
—— In This Article
Key Takeaways
- Traditional IRA contributions may be tax-deductible now; withdrawals in retirement are taxed as ordinary income.
- Roth IRA contributions are made with after-tax dollars; qualified withdrawals are tax-free.
- Traditional IRAs require minimum distributions starting at age 73; Roth IRAs have no required minimums during the owner's lifetime.
- Income limits apply to Roth IRA contributions but not to Traditional IRA contributions.
- Your current and projected future tax rate is the central factor in choosing between the two structures.
- A licensed financial adviser can help you evaluate which account type fits your specific situation.
How each account handles taxes
The core difference between a Traditional IRA and a Roth IRA is timing: when you pay taxes on the money.
With a Traditional IRA, contributions may be tax-deductible in the year you make them, depending on your income and whether you or your spouse have access to a workplace retirement plan. The money grows tax-deferred, meaning you owe no taxes while it stays in the account. When you withdraw funds in retirement, those withdrawals are taxed as ordinary income at your rate at that time.
A Roth IRA works in reverse. You contribute money that has already been taxed, so there is no upfront deduction. The account grows tax-free, and qualified withdrawals in retirement, including earnings, are not taxed. To qualify as tax-free, withdrawals generally must be taken after age 59 and a half and after the account has been open for at least five years.
| Criterion | Traditional IRA | Roth IRA |
|---|---|---|
| Tax treatment on contributions | May be tax-deductible | After-tax, no deduction |
| Tax treatment on withdrawals | Taxed as ordinary income | Tax-free (if qualified) |
| Income limits to contribute | None | Yes, phases out at higher incomes |
| Required minimum distributions | Yes, starting at age 73 | None during owner's lifetime |
| Five-year rule for earnings | Not applicable | Account must be open 5 years for tax-free earnings |
| Best tax scenario | Lower tax rate in retirement | Same or higher tax rate in retirement |
This tax structure difference is what makes the choice between the two accounts largely a question about your current versus future tax rate. There is no universally correct answer, and projecting future tax rates involves uncertainty. Consulting a qualified financial adviser is worth considering before committing to one approach.
Contribution limits, income rules, and required distributions
For 2024, both account types share the same annual contribution limit: $7,000, or $8,000 if you are age 50 or older. That limit applies to the combined total across all your IRA accounts, not per account.
Roth IRAs have income eligibility limits. For 2024, the ability to contribute phases out for single filers with modified adjusted gross income between $146,000 and $161,000, and for married couples filing jointly between $230,000 and $240,000. Traditional IRAs have no such ceiling for contributions, though the tax deductibility of those contributions phases out at certain income levels for people covered by a workplace plan.
IRS limits change periodically
Contribution limits and income phase-out thresholds for both IRA types are adjusted periodically for inflation. The figures cited here reflect 2024 IRS guidance. Always verify current limits on IRS.gov or with a tax professional before making contribution decisions.
Required minimum distributions (RMDs) are another meaningful difference. Traditional IRA owners must begin taking RMDs at age 73 under current IRS rules, whether or not they need the income. Roth IRA owners are not subject to RMDs during their lifetime, which allows the account to keep growing and gives more flexibility in managing taxable income in retirement. For readers thinking about how to sequence withdrawals across accounts, this distinction matters considerably.
Longer-term planning considerations
Account structure affects more than just annual taxes. It shapes how much flexibility you have as your financial picture changes over decades.
Because Roth withdrawals are tax-free, they do not count toward the income thresholds that can affect Medicare premium surcharges or the taxability of Social Security benefits. That can matter for retirees managing income from multiple sources. Living longer than expected puts additional pressure on retirement assets, and tax-free income can help stretch a portfolio further.
Inflation also interacts with these accounts in ways worth understanding. A dollar deducted today may buy less by the time you pay taxes on it in retirement, which can cut against the Traditional IRA advantage if inflation runs high. The effect of inflation on retirement income is worth factoring into any long-term account comparison.
Some people hold both account types simultaneously, contributing to each in different years based on income changes, life events, or tax planning needs. Adjusting your spending plan after 60 can also reveal whether your withdrawal strategy still fits your actual expenses.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Contribution limits, income thresholds, and distribution rules are subject to change. Consult a licensed financial adviser or tax professional for guidance specific to your situation.
Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile